
Upgrade your ad spend from Chase to Opal
Opal is built for anyone spending at scale on ads: agencies, performance marketers, media buyers, and ecommerce and DTC brands running serious budgets across Google, Meta, TikTok and other advertising platforms. Chase Ink Business Preferred is a popular small business card that counts social and search advertising among its bonus categories. Here's how the two compare once advertising is your largest line item.

Is Opal or Chase better for high-volume ad spend?
Opal is the more specialized choice for a business running high-volume digital advertising: up to 1.5% cashback on eligible ad spend with no annual cap, credit limits up to $10M sized on the media you manage, unlimited free virtual cards organized by client, platform and campaign, real-time visibility, no annual fee, and no personal guarantee or hard credit check.
Ink Business Preferred pays 3X points on social media and search engine advertising until you reach $150,000 of combined bonus-category spend in an account year, then 1X. The officer who opens the account shares responsibility for the balance with the business. Keep Chase for travel and company expenses, and put the ad spend on Opal.
Chase product terms verified October 2026 and subject to change. Review the Ink Business Preferred product page and Pricing & Terms before applying. Chase, Ink Business Preferred and Ultimate Rewards are marks of JPMorgan Chase. Opal is not affiliated with or endorsed by JPMorgan Chase. Opal credit availability, limits and cashback rates are subject to underwriting, product availability and applicable terms.
Your credit should match the ad spend you manage
Ink Business Preferred is a traditional business credit card. Accounts are subject to Chase's credit approval, and Chase sets the credit line when the account opens. For ordinary company spending that works well, and a growing small business can build its own credit history on it.
High-volume advertisers meet the limit from a different direction. An agency, an ecommerce brand or an in-house performance team may run $300,000 or $500,000 a month in media, far more than its own operating expenses, and a line set at approval may not keep pace with campaigns that scale quickly.
Opal sizes limits up to $10M on managed ad spend, cash flow and underwriting, so capacity grows with the advertising you run.
Liability follows the account too. Chase's offer details state that the Authorizing Officer, together with the business, is responsible for repaying all balances on the account, including charges on employee cards. When several hundred thousand dollars a month of a client's media runs through that account and the client pays late, the responsibility sits with the person who signed.
Opal requires no personal guarantee and no hard credit check, and eligibility is assessed on the spend you manage. The Opal Card is paid in full once a month, and you can reach a person on Opal's team 24/7 by email, phone or online meeting when a question comes up.
Your ad spend outgrows a $150,000 bonus cap fast
Ink Business Preferred is the Chase card most advertisers reach for, and with reason. Advertising purchases made with social media sites and search engines earn 3X Ultimate Rewards points, alongside travel, shipping, and internet, cable and phone services. At small-business volume, that is a real advertising reward.
The 3X rate covers the first $150,000 of combined purchases across all four categories each account anniversary year, and after that Chase returns those purchases to 1X. Travel, shipping and phone bills draw on the same $150,000, so the cap arrives sooner for any business using the card across categories.
A business placing $200,000 a month runs $2.4M of ad spend a year and clears the whole 3X allowance inside the first month. Here is how the rest of that year works out on Ink Business Preferred.
That is 2,700,000 Ultimate Rewards points for the year, worth $27,000 redeemed as cash back, before the $95 annual fee. The same $2.4M of ad spend on Opal earns up to $36,000 in cash, with no annual cap and nothing to redeem. The gap widens with volume: at $500,000 a month, Ink Business Preferred returns about $63,000 a year, against up to $90,000 on Opal.
Which platforms count matters as well. Chase defines the category as advertising bought directly from social media sites and search engines, and notes that advertising purchased through a third party may not qualify. Retail media and programmatic platforms are not named in that definition. Opal pays up to 1.5% on eligible ad spend across Google, Meta, TikTok, Snapchat, LinkedIn, Amazon, The Trade Desk and more, at the same rate on every platform.
As David Azar, founder and CEO of Outsmart Labs, put it after moving to Opal: "The cashback gives us more value than points, and the team is incredibly responsive."
Cards organized around clients, platforms and campaigns
Chase adds employee cards at no additional cost, each with its own spending limit, and lets the account owner monitor employee purchases in real time. That structure is organized around people, with one card per employee drawing on one shared account.
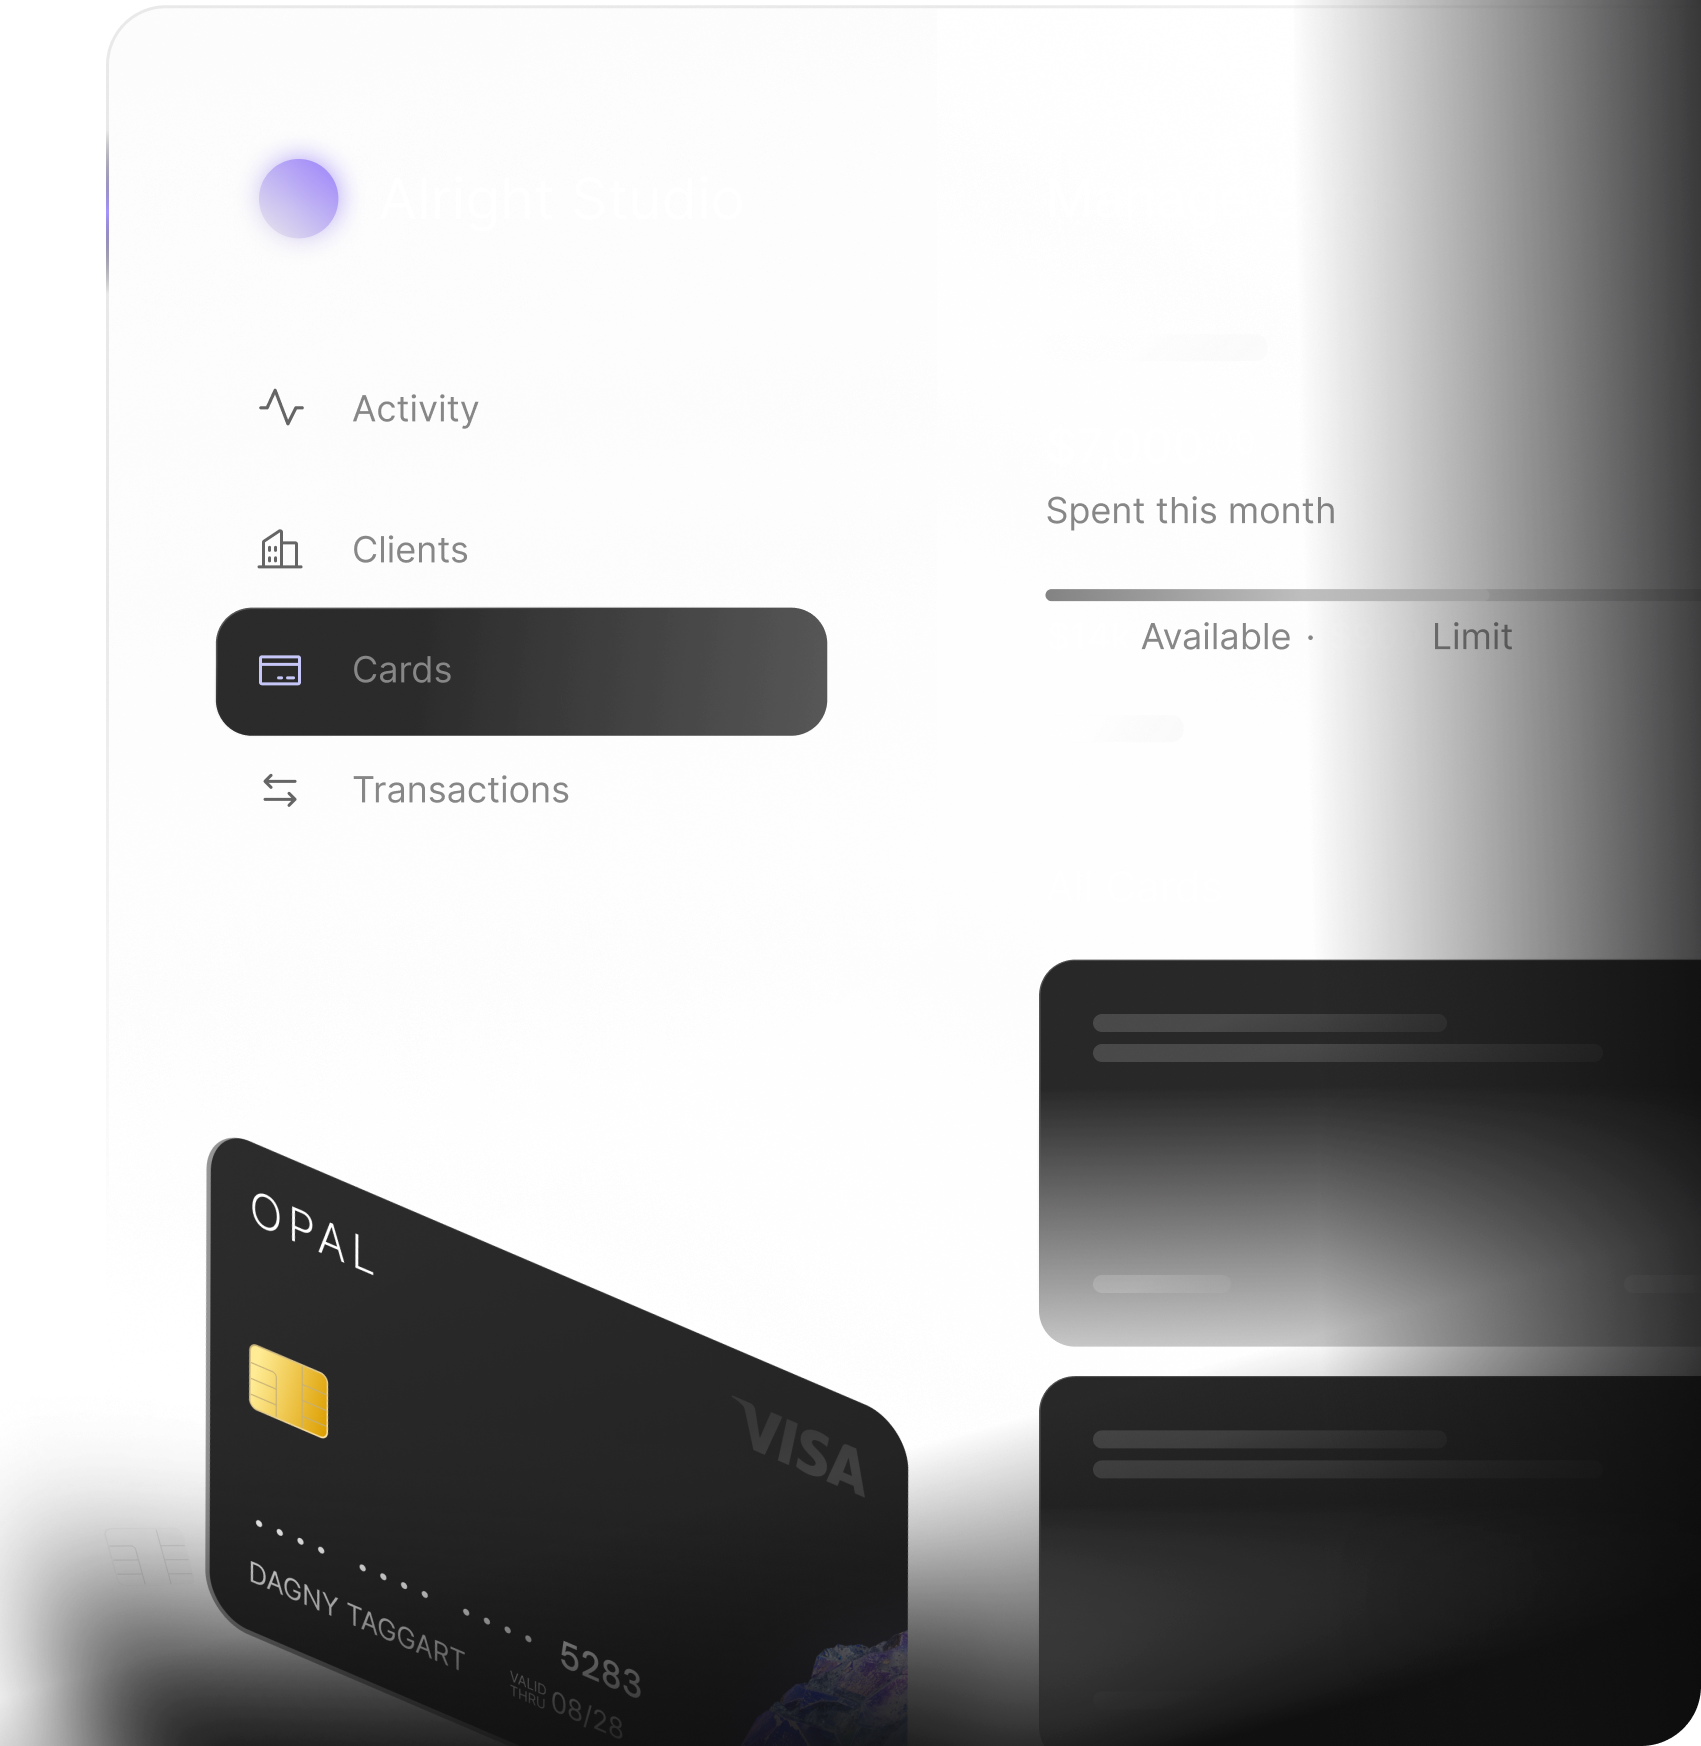
Advertising runs on clients, platforms and campaigns, and Opal organizes cards the same way: one card for a client's Meta spend, another for their Google spend, another again for the next client. Every Opal card can be locked to one platform, given its own spend limit and issued to a team member with their own permissions, and Opal enforces those limits automatically so nobody overspends a client budget. New cards are created instantly, so a new campaign never waits on one.
The structure carries into the books. Transactions reach QuickBooks or Workday already categorized by client, platform and campaign, and you see every one of them in real time rather than at statement time. Agencies working from pre-funded client budgets can also use Opal's client-funded card model, so client money funds client media. Outsmart Labs, a Miami digital agency, recovered 15 hours per week after moving to a per-client card structure on Opal.
Invoice billing takes your largest expense off the card
At high volume, some Meta and Google advertisers are billed by invoice rather than by card. That takes the largest expense in the business out of every card rewards program at once, Chase's bonus categories included.
Opal Ad Pay is built for that. It detects authorized advertising invoices, shows upcoming amounts and due dates in one place, and lets teams settle them with Opal credit or a connected card, extending the cash-flow window by up to 55 days. Payments on Opal credit carry a 3% processing fee, offset by the cashback earned on eligible spend, and payments on a connected card carry a 3.5% fee.
Keep Chase for the rest of the business
Opal cards are designed for supported advertising and media platforms, so most teams keep a general business card for everything else. A Chase Ink card can carry travel, shipping, software, phone bills and day-to-day company purchases, while Opal carries the advertising on credit sized for it. Running both keeps ad spend in its own structure from the first transaction, and it leaves Chase's $150,000 bonus allowance free for the categories that don't run through Opal.
Who Opal is for
Opal is the right fit if you are:


Outsmart Labs faced these same challenges. After switching, they recovered 15 hours per week in reconciliation time and added a recurring cashback revenue stream on client spend they were already running.
15+ h per week
15+
Give your ad spend a card built for it.
Chase covers the rest of what a business buys. Opal covers the advertising: up to 1.5% cashback on eligible ad spend with no annual cap, credit limits up to $10M with no personal guarantee or hard credit check, unlimited free virtual cards with per-card limits and merchant locks, real-time visibility, Ad Pay for Meta and Google invoices, and reconciliation that syncs to QuickBooks or Workday. Apply online in 2 to 3 minutes, with a person available 24/7.
Frequently asked questions
For high-volume ad spend, yes. Ink Business Preferred's 3X advertising rate covers the first $150,000 of combined bonus-category spend each account year, roughly $12,500 a month, and then drops to 1X. Opal pays up to 1.5% cashback on eligible ad spend with no annual cap, so at $2.4M a year it earns up to $36,000 in cash against $27,000 on the Chase card. Opal also adds credit limits up to $10M sized on managed ad spend, cards organized by client, platform and campaign, real-time visibility, reconciliation that syncs to QuickBooks or Workday, no annual fee, no personal guarantee and no hard credit check.
Ink Business Preferred. Advertising purchases made with social media sites and search engines earn 3X Ultimate Rewards points, together with travel, shipping, and internet, cable and phone services. The 3X rate applies to the first $150,000 in combined purchases across those categories each account anniversary year, after which they earn 1X.
Once combined spend across advertising, travel, shipping, and internet, cable and phone services reaches $150,000 in an account anniversary year, Chase returns those purchases to 1X with no maximum. The effective rate on advertising falls as annual ad spend moves past the cap, and it falls sooner if other bonus categories are drawing on the same allowance.
No. Opal does not require a personal guarantee or a hard credit check, and eligibility and credit capacity are assessed on managed ad spend, cash flow and underwriting. Chase customers should review the Pricing & Terms and Cardmember Agreement for their card. Chase's offer details for Ink Business Preferred state that the Authorizing Officer, together with the business, is responsible for repaying all balances on the account.
Chase's category covers advertising purchases made directly with social media sites and search engines, and Chase notes that advertising bought through a third party may not qualify. Retail media and programmatic platforms are not named in that definition, so whether a given charge earns 3X depends on how Chase categorizes the merchant. Opal's cashback covers eligible ad spend across Google, Meta, TikTok, Snapchat, LinkedIn, Amazon, The Trade Desk and more.
Yes, and many teams do. A business can keep a Chase Ink card for travel, shipping, software and other general company expenses while using Opal for digital advertising and client media spend. The two serve different jobs and run side by side without any conflict.
See how Opal compares.

Opal vs Ramp
Agency ad-spend workflows next to Ramp's broader expense and finance platform.
Opal vs Brex
Credit capacity, virtual cards and reconciliation for agencies.
Opal vs Mercury
Opal's ad-spend credit model next to Mercury's business banking and cards.
Opal vs Amex
Business Gold and Platinum on rewards, annual caps and personal liability.
Opal vs Slash
Cashback, credit capacity, client budgets and Meta invoice payments.
Opal vs Dash.fi
Cashback terms, eligible platforms and credit limits at high volume.