
Business Credit Cards vs Spend Management Platforms: What Finance Teams Need to Know
Business credit cards vs spend management platforms is a choice between a product that lends a business money to pay merchants and a system that decides who may spend, on what, and with whose sign-off.
To choose between them, compare both on 8 points: controls, approvals, virtual cards, visibility, accounting workflows, rewards, liability, and the kind of team each option suits.
The categories now blur. Card issuers add employee limits to products on the Visa and Mastercard networks, while spend management providers issue cards through partner banks, usually insured by the Federal Deposit Insurance Corporation (FDIC).
The rules underneath stay separate: Regulation Z, a Consumer Financial Protection Bureau (CFPB) rule, sets liability for unauthorized card use, and Internal Revenue Service (IRS) Publication 583 sets out which records prove a business expense.
U.S. agencies and brands running Meta Ads, Google Ads, and TikTok budgets feel the gap first, because their largest cost moves through cards daily.
Key Takeaways
A business credit card solves a payment and credit problem, while a spend management platform solves a governance problem: who can spend, with which merchants, and with whose approval.
The categories overlap because card issuers add employee limits and platforms issue their own cards, so judge each option by where the rule is set and who sets it.
A card does not remove the paperwork: Internal Revenue Service (IRS) Publication 583 treats a card statement as proof of payment, not proof of a business expense, so invoices and sales slips still matter.
Regulation Z caps a cardholder's liability for unauthorized use at $50, but an issuer and an organization with 10 or more employee cards may agree to different terms for the business.
Owner-led businesses with 1 or 2 spenders often need only a card, while teams with many spenders, recurring vendors, or client budgets usually need a platform or a card that comes with one.
What Is the Difference Between a Business Credit Card and a Spend Management Platform?
A business credit card is a financing product, and a spend management platform is an operating layer for spending. One decides how a purchase gets paid, the other whether it should happen and how it is recorded.
What a Business Credit Card Does
An issuer underwrites your business, sets a credit line, and gives you cards that work wherever the network is accepted. You get a monthly statement, a due date, and usually rewards. Credit cards let you carry a balance at interest, while charge cards require the full balance every cycle.
Controls on most business cards stop at the account. Rules about vendors, projects, or approvers usually live in another tool.
What a Spend Management Platform Does
A spend management platform sits between your team and the money. It issues or connects cards, sets rules per card, routes requests to an approver, collects receipts, and pushes coded transactions into accounting software. Our glossary entry on what spend management covers sets out the full scope.
Before a purchase, a rule or an approver decides whether the charge goes through. Afterward, each transaction arrives tagged to an owner, a budget, and a general ledger account.
Where the Two Overlap
Many card programs now add virtual numbers and employee limits, and most modern spend management platforms issue their own card through a partner bank. That is why a search for spend management vs corporate card often surfaces the same product twice.
The useful test is who writes each rule. If the issuer sets the ceiling and approvals happen in email, you have a card. If your team writes the rules and the card enforces them at purchase, you have a platform.
How Do Business Credit Cards vs Spend Management Platforms Compare?
The clearest comparison runs line by line, using the questions finance asks after something goes wrong. The table shows typical behavior, though individual products vary.
Side-by-Side on 8 Points
|
Point |
Traditional business credit card |
Spend management platform |
|---|---|---|
Controls |
One credit line set by the issuer, sometimes with a lower cap per employee card |
Limits, merchant rules, and end dates set by your team on each card |
Approvals |
Handled outside the card, in email, chat, or a spreadsheet |
Requested and approved inside the platform, linked to the card |
Virtual cards |
Few or none, often for online checkout only |
Created on demand for each vendor, team, project, or client |
Visibility |
Posted transactions and the statement balance |
Each charge shown against its budget and owner as it posts |
Accounting workflows |
Statement export coded by hand |
Transactions synced with owner and account code attached |
Rewards |
Points or category bonuses, often capped, with annual fees on premium tiers |
Varies by provider, from none to flat cashback |
Liability |
Often backed by the owner's personal guarantee |
Varies; some programs underwrite the business alone |
Best suited to |
Owner-led businesses with few cardholders |
Teams with many spenders, budgets, or recurring vendors |
Treat each cell as a demo prompt. Ask the provider to show the setting live, because a feature in a help article can still be missing from your plan.
How Do Business Card Controls Differ From Corporate Spend Controls?
Business card controls are set by the issuer around the account, and corporate spend controls are set by your team around each purchase. That difference decides whether a rule stops a charge or only shows up in a report.
Limits Set by the Issuer
On a traditional card, the issuer sets your total line from your financials and, often, the owner's personal credit. You can sometimes cap an employee card below that line, but the cap usually applies to every merchant. Anything finer, such as one vendor per card or a fixed end date, needs separate software.
Rules Set by Your Team
A platform lets finance write rules for each card: a monthly ceiling, a merchant restriction, an expiry date, and an owner. Those rules are checked at authorization, so a purchase outside them is declined, not flagged weeks later. That timing gets its own walkthrough in our piece on card control timing.
Where Approvals Happen
With a card alone, approval happens away from the payment, and nothing connects the yes to the charge. A platform stores the request, the approver, and the approved amount against the card. When an auditor asks who signed off, you answer from one record instead of old messages.
What Do Virtual Cards and Visibility Look Like on Each Option?
Both options can offer virtual cards, but they differ in how many and what each card is for. Visibility splits the same way: a card shows spend after it posts, and a platform shows it against a budget as it happens.
Virtual Cards as a Feature or a Workflow
Some business cards offer a few virtual numbers for online checkout. On a platform, the virtual card is the unit of control: one per vendor, team, project, or client, each with its own ceiling and owner. Closing one card leaves everyone else's spending untouched.
Seeing Spend Before the Statement
A card portal shows posted transactions and a running balance. A platform shows each charge beside its budget, its owner, and the room left. For a team paying ad platforms daily, that means catching an overspend on day 3 instead of day 31.
How Does Each Option Handle Accounting Workflows?
Accounting is where the expense management vs business credit card question gets settled. A card changes who pays up front, but your books and the tax rules ask the same of every purchase.
Why a Card Does Not Remove the Receipt
IRS Publication 583 accepts a credit card statement as proof of payment when it shows the amount charged, the payee's name, and the transaction date. The same guidance says proof of payment alone does not establish a deduction, so you still keep the invoice or sales slip showing what the cost was for. A statement shows who was paid, and the receipt shows what was bought.
Expense Management vs Business Credit Card Reimbursement
Expense management software grew up around reimbursement: the employee pays, files a claim with a receipt, and waits to be repaid.
A business credit card removes the out-of-pocket step. The receipt and the coding still have to happen, so teams either pair cards with an expense tool or move to a platform that captures both at purchase.
What Syncs to the Ledger
A card statement exports dates, merchants, and amounts for someone to code by hand. A platform sends transactions with the owner, budget, and account code attached. If your books run on QuickBooks, our QuickBooks sync walkthrough shows which fields to map first.
How Do Rewards Compare Between Cards and Platforms?
Rewards are where traditional cards look strongest on paper. Read the cap and category rules before comparing rates, because the headline rate rarely covers all your spend.
Points, Multipliers, and Caps
Many business credit cards earn points with bonus multipliers in set categories, sometimes including advertising.
The bonus rate usually stops at an annual cap, after which purchases earn a base rate, and premium tiers carry an annual fee. Points also have to be redeemed, and their worth depends on how you use them.
Cashback on the Spend You Actually Run
Platforms range from no rewards to flat cashback. To compare, multiply your yearly spend in the bonus category by the bonus rate up to the cap, add the base rate on everything past it, and subtract the annual fee. Run that sum for each option with real monthly totals.
Who Is Liable for the Balance on Each Option?
Liability has two parts: who repays the balance, and who absorbs a charge nobody authorized. The binding answer to both sits in the cardholder agreement, not the marketing page.
Personal Guarantees on Small-Business Cards
Many small-business cards ask the owner to sign a personal guarantee, which puts personal assets behind the company's balance. Issuers that underwrite against business results drop it more often. Read the personal guarantee terms closely, and ask what happens to the guarantee if you close the account.
Unauthorized Use and the 10-Card Rule
Regulation Z caps a cardholder's liability for unauthorized use at $50, or less if less was taken before the issuer was notified.
When one issuer provides 10 or more cards for an organization's employees, the issuer and the organization may agree to different liability terms for the business. An individual employee can still be held liable only within the regulation's limits.
Corporate Card vs Business Credit Card Liability
The corporate card vs business credit card distinction mostly comes down to whose credit backs the account.
A business credit card is often underwritten with the owner in view, while a corporate card program places liability on the company, as our corporate card definition explains. Ask each provider in writing whether an employee can ever be asked to carry a balance.
Which Option Fits Your Team?
Fit depends on how many people spend, how many budgets you track, and whether your biggest cost needs its own rules. Start from problems you already have, not features you might use.
When a Card Is Enough
A business credit card covers most needs when 1 or 2 people make most purchases and a monthly review catches problems in time.
Founders comparing the best business credit card for startups usually start here, provided the limit fits monthly spend and the guarantee terms are acceptable.
When You Need a Platform
A modern spend management platform earns its place once purchases need approval before they happen, several teams or clients share one account, or month-end close depends on chasing receipts. The card stays the payment rail, and the platform does the governing.
Run a 7-Symptom Check
Mark each symptom your team has hit in the last quarter:
|
Symptom |
What is missing |
Where the fix sits |
|---|---|---|
The limit runs out before the month ends |
Credit sized to real spend |
Card underwriting |
Charges arrive that nobody approved |
A rule or approver before purchase |
Platform |
Receipts get chased at month end |
Capture at the point of purchase |
Platform |
One statement mixes teams or clients |
A card per owner or budget |
Platform |
A former employee's card still gets charged |
A clear end date or close step per card |
Platform |
The owner personally backs the balance |
Business-only underwriting |
Card terms |
Rewards stop earning partway through the year |
An uncapped or higher-capped rate |
Card terms |
Platform rows need software, which a new card cannot supply. Card rows need different card terms, which software cannot supply.
Govern Your Ad Spend With the Opal Card
If advertising is your largest variable cost, that spend needs a card and a control layer in one place. We designed the Opal Card around that job and keep it scoped there.
What We Provide and Run
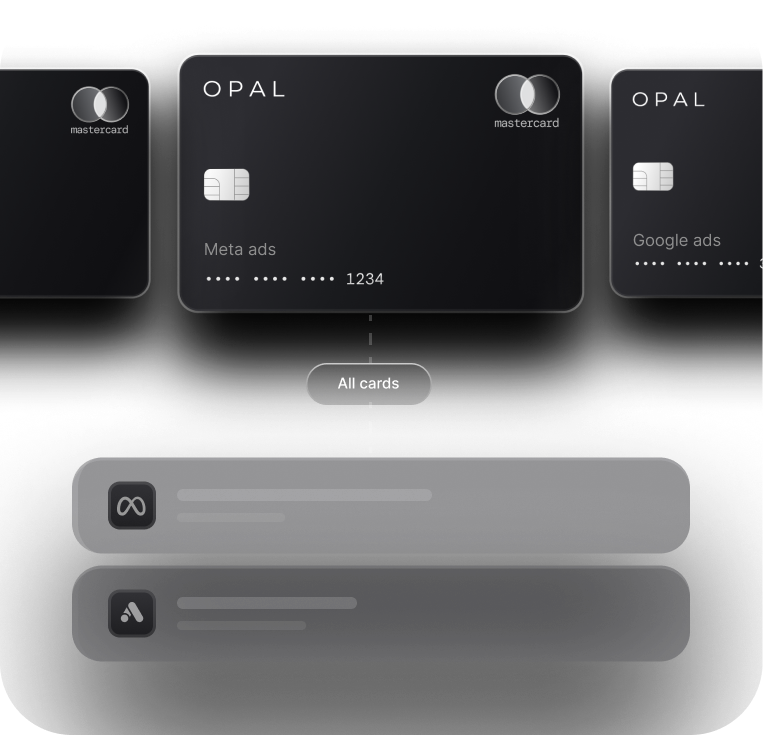
We provide the Opal Card, our charge card for ad spend, and we operate the platform behind it. You can create virtual cards whenever you need them, at no cost, each carrying its own limit, merchant restriction, and expiry date.
Spend approvals, employee permissions, and one dashboard sit in the same account, and transactions flow into QuickBooks or Workday.
The card pays back up to 1.5% of eligible ad spend with no ceiling on earnings, at a rate fixed during approval: 1% on credit accounts, 1.5% on pre-funded accounts. There is no annual or subscription fee, and approval does not depend on an owner's guarantee or a hard inquiry into your credit.
What You Configure and Where the Limits Sit
You decide the card structure, the ceilings, and who approves what. The Opal Card is pay-in-full, with the statement balance debited automatically each month.
We serve U.S.-based businesses only. Card use is limited to supported advertising and media platforms. Keep software, travel, and payroll on another account. When you are ready, apply for Opal and build your first cards.
Frequently Asked Questions (FAQs)
Is a Spend Management Platform the Same as a Credit Card?
No. A spend management platform is software that sets rules, routes approvals, and records spending. Many platforms issue their own cards through a partner bank, so the card and software arrive together, while others work alongside cards you already hold. Confirm which model a provider uses before comparing limits or rewards.
Can You Use a Business Credit Card With a Spend Management Platform?
Sometimes. Some platforms import transactions from cards you already hold, while others enforce rules only on cards they issue themselves. If you want to keep an existing card for its rewards, ask whether the platform's controls decline a charge at authorization or only flag it after posting.
Do Spend Management Platforms Replace Expense Reports?
For card purchases, largely yes, because the platform collects the receipt and coding at the time of purchase. Employees who pay out of pocket still file a claim with the receipt attached, because a statement only proves payment. Most teams keep a short reimbursement process for everything else.
Which Is Better for a Startup, a Card or a Platform?
A single card usually covers a startup with 1 or 2 spenders and one budget. Move to a platform once purchases need approval before they happen, a second team starts spending, or receipts hold up your monthly close. Compare guarantee terms either way, because a personal guarantee follows the owner if the company cannot pay.
Who Pays If an Employee Misuses a Company Card?
Usually the business. Regulation Z defines unauthorized use as use by someone without actual, implied, or apparent authority, so an employee who was given the card generally falls outside it. That makes misuse an internal matter for your spend policy, which is why per-card limits and merchant rules matter before a charge, not after.
Does the Opal Card Work for Non-Advertising Spend?
No. Card use is limited to supported advertising and media platforms, including Meta Ads, Google Ads, and TikTok, so keep payroll, software, and travel on a separate account. Within that scope, you can issue unlimited virtual cards, set a limit and merchant restriction on each, and review spend from one dashboard.
Best Credit Card for Facebook Ads and Meta Ads in 2026
Charge Card vs. Credit Card for High Ad Spend: What Actually Matters
Corporate Credit Card Controls: How Agencies Prevent Unauthorized and Over-Budget Ad Spend