Agency Ad Spend Cash Flow Forecast: Stress-Test 13 Weeks Before a Client Pays Late
An agency ad spend cash flow forecast is a week-by-week projection of the cash an agency holds after it pays ad platforms for client media and before clients reimburse that spend.
The reliable way to build one is to lay out 13 weeks of card repayments, client collections, and operating costs, then rerun the model with 1 lever changed at a time until you find the week your cash or your credit limit gives out.
The method suits agencies, media buyers, and finance leads who front client spend on Meta (Facebook and Instagram), Google Ads, TikTok Ads, and LinkedIn Ads, then invoice clients on net 15 or net 30 terms.
Google's help page on postpay charges says automatic payments are charged at a payment threshold and on the first day of the month, and Meta bills card-funded accounts on a threshold plus a monthly bill date.
The card statement is then debited on a second date, and client cash arrives on a third. In the Small Business Credit Survey run by the Federal Reserve Banks, 51% of employer firms named uneven cash flow as a challenge over the prior 12 months, a category that includes collecting on receivables.
In this article, you'll learn how to build a 13-week model around those 3 dates for an example agency running $200,000 a month in client media. You'll also see how it holds up under 4 stress tests (a late client, a spend increase, an earlier repayment, and a new client) and how to size a reserve from them.
Key Takeaways
A 13-week forecast covers 3 billing months plus a buffer week, which is long enough to show a late invoice from one month colliding with a card repayment in the next.
Every week of the model runs 2 tests: ending cash against a minimum cash floor, and the card balance before each repayment against your credit limit.
In the worked example, the largest client paying 4 weeks late drops cash to $34,000, which is $16,000 below a $50,000 floor, with no change in media spend.
A 30% spend increase leaves cash intact when clients pay before the card is debited, but it pushes the card balance $55,000 past a $400,000 limit in week 11.
Moving the card repayment 2 weeks earlier, ahead of client collections, takes the lowest balance from $114,000 to negative $86,000, so the order of the dates matters more than the amounts.
What Is an Agency Ad Spend Cash Flow Forecast?
It is a weekly table that tracks your operating cash and card balance side by side for 13 weeks, so you see the low point of each before it arrives. A monthly budget hides those low points, because charges, the card debit, and client payments fall in different weeks.
Run 2 Tests Side by Side
The cash test compares ending cash each week with a minimum cash floor, the balance you refuse to go below, such as 2 payroll cycles.
The card test compares the card balance before each repayment with your credit limit, because platforms keep charging while a statement waits to be paid. When a charge would take the balance over the limit, the card issuer declines it, and the ad platform holds the unpaid balance or pauses delivery until a payment clears.
Plan 13 Weeks Instead of 1 Month
Thirteen weeks gives you 3 billing months of 4 weeks plus 1 extra week. That span catches what a 30-day view misses, such as a month 1 invoice arriving late just as the month 1 statement is debited. Between quarterly runs, our rolling weekly forecast covers the shorter 4 to 6 week view.
How Do You Build the 13-Week Model?
Start from a short list of inputs and let every week calculate from them. Keep each input in its own cell, so each stress test changes just 1 number.
Enter the Base Assumptions
The worked example uses these inputs, with statements and invoices closing in weeks 4, 8, and 12:
|
Input |
Example value |
Where to find yours |
|---|---|---|
Media spend charged to the card |
$50,000 a week across 4 clients |
Billing summaries in each ad account, last 4 weeks |
Agency fee billed with media |
15% of media |
Your statements of work |
Client payment terms |
2 weeks after invoice (about net 15) |
Contracts, then actual collection dates |
Card repayment date |
3 weeks after the statement closes |
Your card agreement or latest statement |
Starting cash |
$120,000 |
Operating account balance |
Minimum cash floor |
$50,000 |
Your own rule |
Credit limit |
$400,000 |
Your card dashboard |
Operating costs |
$6,000 a week |
Payroll and overhead, averaged weekly |
Carry Last Month Into Week 0
Week 0 holds what last month left open: a $200,000 card statement debited in week 3, and a 230,000 client invoice (200,000 of media plus a $30,000 fee) collected in week 2. Skip week 0 and the first month looks healthier than it is. Pull both figures from your last card statement and your receivables aging report.
Trace the First Month of Cash
Say you start with $120,000. Week 1 pays $6,000 of costs and ends at $114,000, week 2 collects $230,000 and ends at $338,000, and week 3 pays the $200,000 debit and ends at $132,000.
Meanwhile 3 weeks of $50,000 charges stack on the unpaid statement, so the card reaches $350,000 before that debit clears. Over 13 weeks, the base plan bottoms out at $114,000 in week 1, and the card peaks at $350,000 in weeks 3, 7, and 11, leaving $50,000 of headroom.
What Happens When Your Largest Client Pays 30 Days Late?
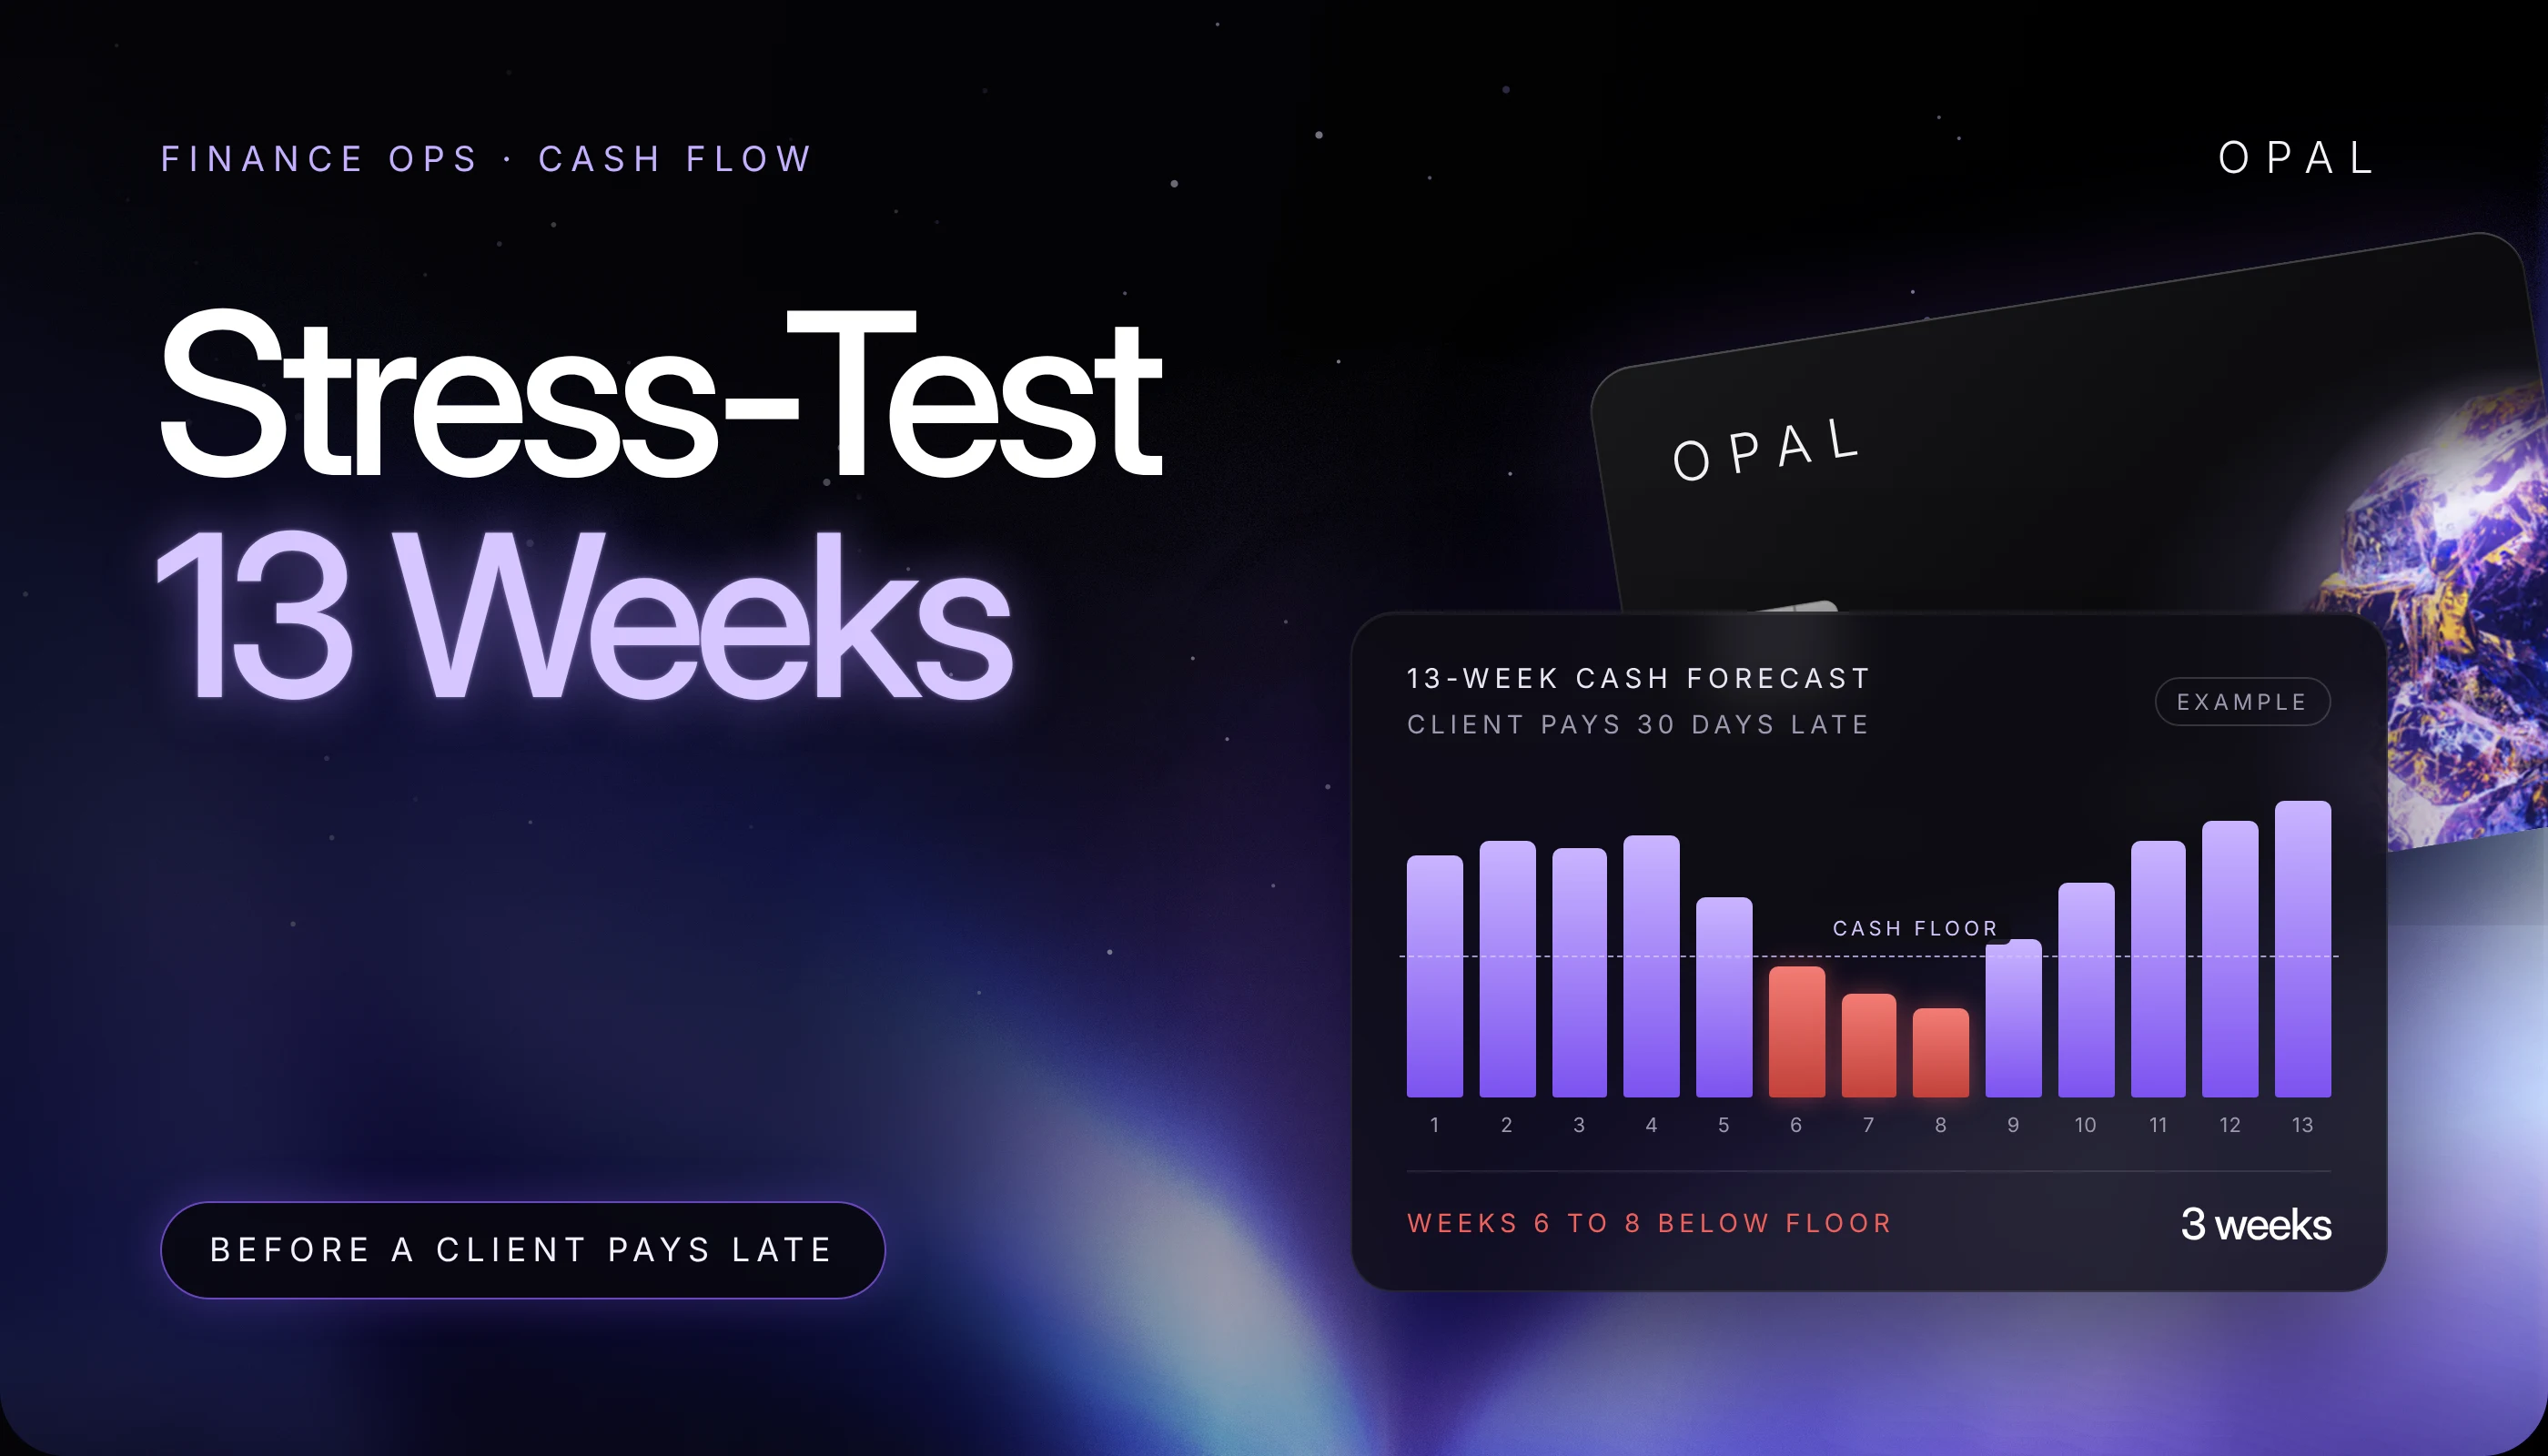
In the example, cash drops below the floor for 3 weeks and bottoms out at $34,000 in week 9, with spend unchanged. The late money was due in week 6, and the $200,000 card debit still lands in week 7.
Read the Week-by-Week Damage
The largest client accounts for 40% of each invoice, so $92,000 of the month 1 invoice arrives in week 10 instead of week 6. Week 6 ends at $252,000, the week 7 debit takes cash to $46,000, and 2 more weeks of costs leave $40,000 and then $34,000. Holding the floor would have taken $16,000 more in starting cash.
Find Your Break-Even Delay
Rerun the late-client test at 1, 2, and then 3 weeks late, and watch for the first week below the floor. Here, 1 week late does no harm because the payment lands with the debit, while 2 weeks late leaves cash at $46,000 for a week.
That delay tells you when to start chasing, so an invoice a few days overdue calls for a phone call that week. Our guide to a media credit policy covers the contract terms behind it.
How Much Can Media Spend Rise Before Your Card Limit Breaks?
In the example, a 30% increase from week 5 never threatens cash, but it pushes the card balance to $455,000 in week 11, $55,000 over the $400,000 limit. Spend growth on a card shows up first as limit pressure.
Watch the Balance Before Each Debit
At $65,000 a week, the month 2 statement closes at $260,000 and waits until week 11 to be debited. The $195,000 left after the week 7 debit plus 4 weeks of $65,000 charges brings the balance to $455,000.
Cash moves the other way, because the $299,000 month 2 invoice arrives in week 10, a week before the debit. An agency watching its bank balance alone would miss the week 11 declines.
Make Room Before the Increase Starts
Ask your card provider to review the limit before the higher budget goes live, sending 90 days of billing history and the client's signed budget change.
Otherwise, ask the client to prepay or phase in the increase, then rerun the test. Between runs, track days of cover weekly on each card.
Why Does Your Repayment Date Matter More Than Your Balance?
A debit that lands before client cash forces you to fund the whole statement from reserves. Moving the example's repayment from 3 weeks after close to 1 week takes the lowest balance from $114,000 to negative $86,000, with spend and clients unchanged.
Run the Earlier Repayment Test
With a 1-week gap, statements are debited in weeks 1, 5, 9, and 13, each a week before the collection it depends on.
Cash goes negative in each of those weeks, bottoming at negative $86,000 in week 1, and holding the floor would take $136,000 more in starting cash. Client terms stretching from net 15 to net 30 create the same pattern from the other side.
Line Up Client Terms With the Debit
Write 4 dates for each billing month into the model: statement close, card debit, client invoice, and client due date. Every client due date should fall at least 1 week before the debit it funds.
Here, shortening client terms to 1 week (about net 7) keeps cash above the floor, with a low of $126,000. Our comparison of client media funding routes covers prepaid setups for clients who refuse shorter terms.
Can Your Cash Flow Absorb a New Client?
It can if you plan for both its first invoice and its card charges. In the example, a client spending $25,000 a week from week 5, a $3,000-a-week hire to service it, and a first invoice paid 4 weeks late leave $5,000 in week 13 and break the card limit in week 7.
Model the New Account's First 13 Weeks
The new client adds $100,000 to the month 2 statement, so the week 11 debit grows to $300,000, while its first $115,000 invoice, due in week 10, arrives in week 14. Cash falls to $23,000, $14,000, and $5,000 in weeks 11 to 13, and the card goes over the limit at $425,000, $450,000, and $525,000 in weeks 7, 10, and 11.
Decide What to Change Before You Sign
The 2 failures need separate fixes. If the first invoice pays on terms, the lowest balance recovers to $111,000, yet the card still breaks the limit in weeks 7, 10, and 11.
Before signing, agree on first-month terms and finish vendor setup so the first invoice isn't stuck in approval. Then raise the limit or start at a lower weekly spend, and rerun the growth scenario until cash and the card both pass.
How Big a Cash Reserve Does Each Scenario Need?
Each scenario needs your minimum cash floor minus its lowest balance, on top of your starting cash. In the example, that ranges from $0 for the spend increase to $136,000 for the earlier repayment date.
Compare the 4 Stress Tests
Running all 4 tests from the same base inputs gives this comparison:
|
Scenario |
Lowest cash (week) |
Weeks below $50,000 floor |
Reserve top-up |
Peak card balance |
First week over $400,000 limit |
|---|---|---|---|---|---|
Base plan |
$114,000 (week 1) |
0 |
$0 |
$350,000 |
None |
Largest client 4 weeks late |
$34,000 (week 9) |
3 |
$16,000 |
$350,000 |
None |
Spend up 30% from week 5 |
$114,000 (week 1) |
0 |
$0 |
$455,000 |
Week 11 |
Repayment 1 week after close |
Negative $86,000 (week 1) |
4 |
$136,000 |
$250,000 |
None |
New client, first invoice late |
$5,000 (week 13) |
3 |
$45,000 |
$525,000 |
Week 7 |
Hold Reserves for the Risk You Can't Fix
Hold enough for the scenarios you can't prevent, and fix the rest at the source. A late payer sits outside your control, so the $16,000 top-up is worth holding, while the repayment and growth failures respond to new terms and a limit review. Rerun all 4 tests whenever you add a client, change terms, or change cards.
Run Your Client Media on the Opal Card
The model flags 2 failure points, cash below your floor and a card balance above your limit. We provide a charge card built for ad spend, and you set it up around your forecast's dates.
See What Every Account Includes
We provide the card, and we may periodically review your performance and offer a credit increase.
Unlimited virtual cards come at no cost, so each client, ad account, platform, or campaign gets its own card with its own spend limit, merchant restriction, and team permissions.
Eligible ad spend earns 1% cashback on credit accounts and up to 1.5% on pre-funded accounts, uncapped, and we confirm your rate at approval. You pay no annual fee, sign no personal guarantee, and face no hard credit check, and transactions sync to QuickBooks.
Check the Fit Before You Apply
You configure the cards, limits, and approvals. The Opal card is a pay-in-full charge card, so the full statement balance is debited automatically on each monthly due date, which becomes your repayment week in the model. If that debit fails, the card can be locked until the balance is repaid.
We serve U.S.-based businesses, and the card works on supported advertising and media platforms, so keep a general business card for other costs.
Opal Ad Pay is a separate product for Meta and Google invoices, currently offered by waitlist, with a 3% fee on Opal credit (1% cashback brings the net cost to 2% where eligible) or 3.5% on a connected card, and it extends the cash-flow window by up to 55 days.
The application takes 2 to 3 minutes, and virtual cards usually arrive within 24 to 48 hours. See the setup on Opal for agencies, then apply from our site or book a demo.
Frequently Asked Questions (FAQs)
Agency owners and finance leads raise these questions once they start forecasting media cash. Each answer stands on its own, so jump to the one you need.
What Is a 13-Week Cash Flow Forecast for an Agency?
A 13-week cash flow forecast for an agency is a weekly projection of cash in and out across 3 billing months plus 1 week. It lists collections, card or platform payments, and operating costs by week, so the agency spots its lowest balance early.
How Do I Build an Ad Spend Cash Flow Template in a Spreadsheet?
Put inputs on 1 tab: weekly media spend, fee rate, client payment terms, card repayment timing, starting cash, cash floor, and credit limit. On a second tab, give each week a column and calculate charges, debits, collections, and ending cash. Copy that tab once per stress test.
How Do Clients Paying Late Affect Agency Cash Flow?
A late client payment hurts most when it misses the card payment it was meant to fund. In one worked example, a client paying a $92,000 share of an invoice 4 weeks late left cash below a $50,000 floor for 3 weeks, because a $200,000 card debit landed in the gap.
How Much Working Capital Does a Marketing Agency Need for Media Buying?
Enough to keep cash above a chosen floor in the worst scenario you can't prevent. Run a 13-week model under a late payment, a spend increase, and a new client, and subtract each lowest balance from the floor. The largest gap you can't fix through terms or limits is your reserve target.
Do Meta and Google Ads Billing Rules Change My Cash Flow Plan?
Yes. On automatic payments, Meta and Google charge at a payment threshold and on a monthly date, so charges come more often as spend grows. Google's help page on monthly invoicing describes those accounts running on credit Google extends, repaid under agreed terms, so model each account on its actual setting.
Agency Ad Spend Financing: How to Fund Client Media Without Tying Up Your Own Cash
How Opal’s QuickBooks Integration Works for Agency Ad Spend
Agency Ad Spend Management: How to Run Client Media Without Sharing Credit Cards